A trainee mortgage adviser role is usually the first step between gaining mortgage knowledge and becoming confident enough to advise clients in a real working environment. The role combines further learning with practical experience, supervised client work, administration and an increasing understanding of how the mortgage process works from enquiry through to completion.
For someone starting their first job in mortgage advice, the experience can feel quite different from studying CeMAP. Passing CeMAP exams gives you important knowledge, but a trainee role is where you begin learning how to apply that knowledge to real customers, real lender criteria and real cases.
The exact role varies between employers. Some trainees begin with administration or observation before gradually taking on client conversations. Others work within structured academies or development programmes. You should therefore expect a learning curve rather than assuming you will immediately spend every day giving mortgage advice.
What Does a Trainee Mortgage Adviser Do?
A trainee mortgage adviser learns how to apply mortgage knowledge within a regulated working environment while developing the practical skills needed to deal with clients and mortgage applications.
Depending on the employer and your stage of development, this could include observing experienced advisers, speaking with clients, gathering information, completing fact-finds, researching mortgage options, maintaining client records and helping applications progress.
Your responsibilities are likely to increase as you demonstrate that you can complete tasks accurately and follow the organisation’s processes.
It is important to distinguish this from simply passing CeMAP. The qualification provides the knowledge required for mortgage advice, but employers will normally have their own processes for training, supervision and assessing whether a new adviser is ready to undertake different activities.
What Does a Typical Day Look Like for a Trainee Mortgage Adviser?
There is not one standard working day because mortgage adviser roles vary considerably between banks, building societies, brokerages and other mortgage businesses.
However, a trainee might spend time on activities such as:
- reviewing new mortgage enquiries and existing cases
- contacting clients for information or documents
- observing or participating in client appointments
- completing or updating fact-finds
- researching lender products and criteria
- preparing case information for review
- updating customer records and internal systems
- speaking with lenders or other parties about applications
- completing training and development activities
- discussing cases with a supervisor or experienced adviser
- following up outstanding information.
Some days may be heavily focused on clients, while others involve more administration, research or training.
This is one reason new advisers sometimes find the transition from CeMAP study surprising. Mortgage advice is not simply a matter of knowing which mortgage product looks suitable. A considerable amount of work can go into understanding a client’s circumstances, documenting the advice and progressing an application.
Will You Give Mortgage Advice Straight Away?
Not necessarily.
Having CeMAP does not automatically mean an employer will expect you to begin handling complete mortgage cases independently from your first day.
A new adviser needs to understand the organisation’s systems, procedures, compliance requirements, lender relationships and approach to dealing with clients. Employers may also have their own competency requirements before allowing someone to undertake particular activities without close supervision.
You might therefore begin by observing appointments, completing sections of the process or working alongside a more experienced colleague.
As your knowledge and practical ability develop, you may be given greater responsibility.
This gradual progression is useful. A classroom or home-study example can be designed to test a particular area of knowledge. Real customers rarely arrive with circumstances that fit neatly into a textbook example.
What Is the Learning Curve Like in Your First Mortgage Adviser Job?
The learning curve can be significant because you are learning a job as well as applying your mortgage knowledge.
CeMAP helps you understand areas such as mortgage products, regulation and the principles surrounding suitable advice. Your first role introduces another layer: how those principles work when dealing with an actual client.
For example, you may need to learn how to:
- ask questions naturally rather than simply reading through a fact-find
- identify when additional information is needed
- explain mortgage terminology clearly
- research lender criteria efficiently
- use mortgage sourcing and customer management systems
- keep accurate case notes
- manage several applications at different stages
- communicate with clients when something changes.
You are also likely to encounter situations you have never previously studied as a straightforward example.
That does not make your CeMAP knowledge irrelevant. It becomes the foundation on which your practical experience is built.
What Support Should a Trainee Mortgage Adviser Receive?
Support structures differ between employers, but trainees would normally expect some form of supervision and development while learning the role.
This could involve working with a manager, supervisor, mentor, trainer or experienced mortgage adviser. Some larger organisations have formal training programmes, while smaller brokerages may provide more direct one-to-one development.
Support might include observing appointments, reviewing completed work, discussing cases, receiving feedback and having someone available when you are unsure how to proceed.
An important part of being a trainee is knowing when to ask for help.
Trying to appear more experienced than you are can create problems. Mortgage cases can involve complex circumstances, and recognising that something needs checking is a valuable professional habit.
The aim is not to know everything immediately. It is to develop the judgement needed to recognise what you know, what you need to check and when a case needs additional support.
What Will an Employer Expect From a Trainee Mortgage Adviser?
Employers are unlikely to expect a trainee to have the knowledge and speed of an experienced adviser. They can, however, reasonably expect professionalism, accuracy and a willingness to learn.
Attention to detail matters particularly because mortgage applications involve financial information, documentation and regulated processes.
Organisation is also important. Once you are dealing with several clients, you need to know which cases require action, which documents are outstanding and when someone needs to be contacted.
Communication matters just as much. Clients may not understand mortgage terminology, and some may be nervous about borrowing a substantial amount of money. A good adviser needs to listen carefully and explain information in a way the client can understand.
Employers may therefore look beyond exam results when assessing a trainee. Your ability to communicate, organise your workload, follow procedures and respond constructively to feedback can all influence how quickly you develop.
How Much Administration Does a Trainee Mortgage Adviser Do?
Potentially quite a lot.
People considering mortgage advice sometimes picture the role mainly as sitting with clients and recommending mortgages. Client advice is important, but administration and case management are substantial parts of many mortgage roles.
Information needs to be gathered and recorded. Documents may need checking. Applications have to be submitted and monitored. Clients need updates, and additional information may be requested as a case progresses.
Accurate records are particularly important within financial services.
For trainees, administration can also be useful because it helps you understand the complete journey of a mortgage application rather than seeing only the advice conversation.
Over time, some workplaces may provide administrative or case-management support to advisers. Others expect advisers to remain closely involved throughout the process.
Is Working With Real Clients Different From CeMAP Study?
Yes. This is one of the biggest adjustments when entering your first mortgage adviser role.
Exam questions provide the information you need to reach an answer. Clients do not.
A client might forget something important, misunderstand a question or be unsure about their own financial arrangements. You may need to ask additional questions before you have enough information to understand their circumstances properly.
There is also a human element that cannot be fully replicated through exam study.
You might deal with first-time buyers who are nervous about the process, homeowners whose previous purchase was many years ago or clients frustrated because a lender has requested additional documents.
Being able to manage those conversations calmly is part of becoming an effective adviser.
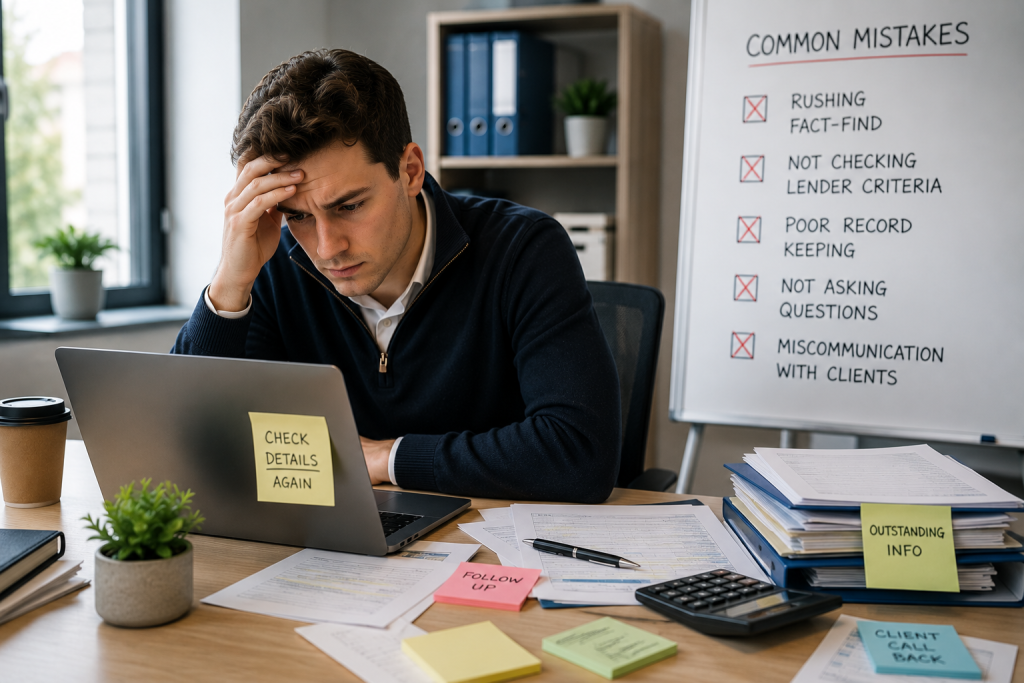
What Mistakes Do New Trainee Mortgage Advisers Commonly Make?
One common mistake is thinking that passing CeMAP means the learning has finished. In practice, it is much closer to the beginning of your professional development.
Another is trying to work too quickly.
Experienced advisers may recognise common situations and know where to research unusual ones. A trainee has not yet built that experience, so attempting to match an experienced colleague’s speed can lead to missed details.
Other early mistakes can include relying too heavily on mortgage sourcing results without checking criteria, using technical language with clients, allowing administration to build up or being reluctant to ask questions.
Feedback is therefore an important part of a trainee role. You will probably have work corrected at some point. The useful question is not whether you made a mistake, but whether you understand why it happened and can avoid repeating it.
How Long Does It Take to Feel Confident as a Mortgage Adviser?
There is no fixed timescale.
Confidence develops through a combination of knowledge, repetition, feedback and exposure to different client situations. The amount of support available and the types of cases you encounter can also affect how quickly you progress.
Your first few client conversations may require considerable preparation. Tasks that initially take a long time can gradually become more familiar as you gain experience.
It is important not to confuse confidence with competence. Feeling comfortable speaking to clients is useful, but good mortgage advice also requires careful research, accurate records and an understanding of your responsibilities.
A trainee who checks something when uncertain may be demonstrating better judgement than someone who confidently guesses.
Is a Trainee Mortgage Adviser Role a Good Way to Start Your Career?
For someone who wants to become a mortgage adviser, a trainee position can provide the practical experience needed to turn CeMAP knowledge into professional capability.
It is not simply an extended training course. You are entering a working financial services environment where clients, deadlines, administration and regulatory responsibilities all matter.
There may be repetitive tasks. Applications can be delayed. Clients can be difficult to contact. Lender criteria can create complications, and some cases will require considerably more work than others.
That is part of the real role.
At the same time, each case gives you experience that cannot be gained solely from study materials. You begin to recognise different client circumstances, become more comfortable asking questions and learn how mortgage applications progress in practice.
The goal of your first trainee mortgage adviser role is not to know everything from day one. It is to build on your CeMAP knowledge, learn from experienced people around you and gradually become capable of handling mortgage cases with greater confidence and responsibility.
Looking for training support?
We offer CeMAP training for learners working towards a career in mortgage advice. Our courses follow the London Institute of Banking & Finance syllabus and are designed to support understanding of mortgage regulation and advice requirements.
Explore our accredited CeMAP training courses
> Futuretrend Financial Training