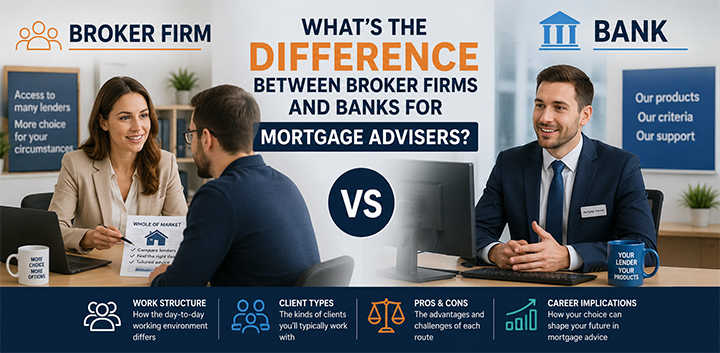
What’s the Difference Between Broker Firms and Banks for Mortgage Advisers?

Broker vs bank mortgage adviser comparison in the UK

If you are starting a career as a mortgage adviser, one of the decisions you may eventually face is whether to work for a mortgage broker firm or a bank or building society. Both can provide a route into mortgage advice, but the day-to-day working environment can be quite different.

The main difference is the range of mortgage products you are able to advise on and the way clients reach you. A mortgage adviser working for a bank or building society will generally advise on products available from that particular lender. An adviser working for a broker firm may have access to products from a wider range of lenders, although the exact scope will depend on the firm and its proposition.

Neither route is automatically better. For a new mortgage adviser, the right environment depends on the type of work you enjoy, the support you need and where you would like your career to develop.

Broker vs bank mortgage adviser comparison in the UK

What Is the Difference Between a Mortgage Broker and a Bank Mortgage Adviser?

A bank mortgage adviser works for a particular lender and advises customers within that lender’s mortgage proposition. Their role is usually part of a larger organisation with established processes, systems, targets and management structures.

A mortgage broker works within an intermediary business. Rather than representing one lender’s mortgage range, the broker researches suitable mortgage products from the lenders available through the firm’s panel or sourcing arrangements.

This creates an important difference in the role.

A bank adviser may become very familiar with one lender’s criteria, products and internal processes. A broker needs to understand how different lenders approach areas such as affordability, property types, employment circumstances and lending criteria.

In both environments, however, mortgage advice remains a regulated activity. Advisers need the appropriate knowledge and competence and must work within the regulatory framework applying to mortgage advice.

How Does the Work Structure Differ Between a Broker Firm and a Bank?

Banks and larger building societies often have a more structured working environment. There may be clearly defined processes covering appointments, compliance, training, supervision and progression.

For somebody entering mortgage advice for the first time, that structure can be useful. You may have a manager, experienced advisers and dedicated compliance or training teams around you.

Broker firms vary much more.

A large national brokerage may have a structure that feels similar to a bank, with centralised systems, training and management. A small independent brokerage could consist of only a handful of advisers and administrators.

That does not necessarily mean a smaller broker provides less support. In some firms, new advisers work closely with experienced brokers and receive considerable one-to-one guidance.

The important point for new entrants is that “broker” does not describe one particular working environment. When considering a role, look at the individual firm rather than making assumptions based purely on whether it is a bank or brokerage.

Do Mortgage Brokers and Bank Advisers Deal With Different Clients?

They can, although there is considerable overlap.

A bank mortgage adviser may speak to existing customers of the bank as well as people who have approached that lender specifically for a mortgage. Clients may arrive through branches, telephone enquiries, online applications or referrals within the organisation.

This means the adviser may spend less time generating their own leads because the organisation already has an established customer base.

A broker firm may receive clients through online enquiries, estate agents, existing customer referrals, professional connections or marketing activity. Depending on the business model, individual advisers may also be expected to develop relationships and generate new business.

Brokers can also encounter clients whose circumstances require them to consider different lenders.

For example, a straightforward employed applicant with a good deposit may potentially meet the criteria of numerous lenders. Someone who is self-employed, has unusual income arrangements or is buying a less conventional property may require more research.

That can make brokerage work varied, but it can also increase the amount of research involved.
Mortgage broker and bank adviser meeting different types of UK mortgage clients

Does a Mortgage Broker Have Access to More Lenders?

Generally, a broker firm can consider a broader range of lenders than an adviser employed by a single bank, but you should not assume that every broker has access to every mortgage available.

Broker firms can operate with different lender panels and product arrangements. Some may offer advice across a broad part of the market, while others may work with a more restricted panel.

A bank or building society adviser is different because their advice is centred on that organisation’s own mortgage proposition.

For somebody considering a career in mortgage advice, this affects the knowledge required.

Within a bank, you may develop detailed knowledge of that lender’s criteria and processes. Within a brokerage, you may need to become comfortable comparing different lenders and recognising where criteria vary.

What Are the Advantages of Working for a Bank as a Mortgage Adviser?

One potential advantage is structure.

Larger financial organisations commonly have established training programmes, management structures, technology, compliance processes and defined responsibilities. This can provide a relatively clear environment in which to learn.

Other possible advantages include:

  • an existing flow of customers and enquiries
  • clearly defined procedures and processes
  • access to internal training and support
  • established compliance and supervision structures
  • potential opportunities to move into other roles within a larger organisation

There can be disadvantages as well.

Your product range will generally be limited to the lender you work for, and larger organisations can have more rigid procedures. Targets and performance measures may also form a significant part of the working environment.

Someone who enjoys clearly defined processes may find that structure helpful. Someone looking for greater independence or a broader range of mortgage cases may eventually prefer another environment.

What Are the Advantages of Working for a Mortgage Broker Firm?

Brokerage can provide exposure to a wider range of lenders, criteria and client circumstances.

That variety can help an adviser build broad mortgage knowledge over time. Instead of asking whether a customer fits one lender’s criteria, the research process may involve identifying which available lender is appropriate for that customer’s circumstances.

Depending on the firm, potential advantages can include:

  • exposure to multiple lenders
  • varied client circumstances
  • broader experience of mortgage criteria
  • opportunities to develop client relationships
  • potential routes towards more independent or self-employed work later in your career

There are also possible disadvantages.

The amount of support varies considerably between firms. Some roles may involve greater responsibility for generating business, managing a pipeline or maintaining professional referral relationships.

Smaller businesses may also have fewer formal career levels than a major bank.

For a new entrant, the name of the role therefore tells you less than the actual support structure behind it.

Is It Easier to Start Your Mortgage Adviser Career in a Bank or Broker Firm?

There is no single best starting point.

A bank may suit someone who wants a highly structured introduction to financial services. A broker firm may suit someone who wants early exposure to different lenders and a wider variety of mortgage cases.

However, the quality of the individual employer is more important than choosing “bank” or “broker” in isolation.

When comparing entry-level mortgage adviser jobs, look at how the employer supports somebody who is newly qualified or still developing competence.

Useful questions include whether you will have a dedicated supervisor, how cases are checked, what training is provided, how leads are generated and what is expected of you during your first few months.

A supportive broker firm may be a much better starting environment than a poorly supported role at a larger organisation, and the reverse can also be true.
New mortgage adviser considering whether to start a career with a bank or broker firm

How Could Your Choice Affect Your Mortgage Adviser Career?

Your first employer does not determine your entire career.

Mortgage advisers can move between banks, building societies, broker firms and other intermediary businesses as their experience develops.

Someone who begins with a bank may build strong experience in client conversations, regulated processes and mortgage applications before moving into brokerage.

Someone starting with a broker may develop broader knowledge of lender criteria and later decide to specialise, move to a larger firm or eventually explore self-employment.

There are also career routes beyond directly advising clients, including compliance, training, management, specialist mortgage advice and business development.

This is why your first mortgage adviser role should be viewed as a place to build practical competence, rather than a permanent choice between two sides of the industry.

Broker vs Bank Mortgage Adviser: Which Is Better?

Neither a broker firm nor a bank is inherently the better place to work as a mortgage adviser.

Banks and building societies can offer a more structured environment with established processes and an existing customer base, while broker firms can provide greater exposure to different lenders, mortgage criteria and client circumstances.

For someone entering the profession, factors such as training, supervision, workplace culture, lead generation and opportunities to gain experience are often more useful considerations than the type of organisation alone.

CeMAP provides the underpinning knowledge needed for a mortgage advice career, but becoming an effective adviser also requires practical development. Your first role is where much of that transition from learning mortgage advice to applying it with real clients begins.

Choosing between a broker and a bank is therefore less about finding the universally “best” option and more about finding the environment in which you can develop the skills, experience and confidence needed for the direction you want your mortgage career to take.

Looking for training support?

We offer CeMAP training for learners working towards a career in mortgage advice. Our courses follow the London Institute of Banking & Finance syllabus and are designed to support understanding of mortgage regulation and advice requirements.

Explore our accredited CeMAP training courses

> Futuretrend Financial Training 
Can You Become a Mortgage Adviser With No Experience?

Person studying CeMAP qualification at a desk with a laptop, representing how to become a mortgage adviser with no previous experience.

Changing careers can feel daunting, especially if you’re moving into a regulated profession like mortgage advice. Many people assume you need years of banking experience or a financial services background before you can even get started. In reality, that’s not the case.

The UK mortgage industry welcomes people from a wide range of professional backgrounds. While experience can certainly help, it is not a requirement for beginning your journey. What matters more is gaining the right qualification, developing the right skills and understanding what employers expect from someone entering the profession.

If you’re asking, “Can I become a mortgage adviser with no experience?“, the answer is yes, but you’ll need to approach it with realistic expectations. Becoming qualified is only one part of the journey. Building confidence, gaining industry knowledge and securing your first role all take time and commitment.

Person studying CeMAP qualification at a desk with a laptop, representing how to become a mortgage adviser with no previous experience.

Can You Become a Mortgage Adviser With No Experience?

Yes. Many mortgage advisers begin their careers without previous experience in financial services.

The profession attracts career changers from retail, hospitality, customer service, administration, teaching, sales and many other industries. These careers often develop valuable transferable skills that employers appreciate.

Experience alone does not qualify someone to provide mortgage advice.

Instead, aspiring advisers normally begin by obtaining the Certificate in Mortgage Advice and Practice (CeMAP) before looking for entry-level opportunities where they can continue developing professionally.

The important thing to understand is that employers are usually looking at your overall potential rather than simply your previous job title.

What Is CeMAP and Why Is It Important?

The Certificate in Mortgage Advice and Practice (CeMAP) is the industry standard qualification for mortgage advisers in the UK. It is awarded by the London Institute of Banking & Finance (LIBF) and meets the Financial Conduct Authority (FCA) education requirements for giving regulated mortgage advice.

For someone with no experience, CeMAP demonstrates several important qualities:

  • Commitment to entering the profession
  • Understanding of mortgage regulation
  • Knowledge of mortgage products and processes
  • Willingness to learn a regulated industry

While passing CeMAP does not guarantee employment, it significantly improves your opportunities because employers know you’ve already invested in learning the foundations of mortgage advice.

Many firms prefer recruiting qualified candidates because they require less initial technical training.

Study desk with mortgage books, laptop, notebook and a model house representing the CeMAP qualification and preparation for a mortgage adviser career.

What Entry Routes Are Available?

There is no single path into mortgage advice.

Depending on your circumstances, you might begin in several different ways.

Train First, Then Apply

Many career changers complete CeMAP before applying for jobs.

This approach allows you to focus on learning first and gives employers confidence that you’re serious about entering the profession.

Typical searches include:

  • CeMAP jobs
  • Trainee mortgage adviser jobs
  • Mortgage adviser jobs for beginners
  • Junior mortgage adviser roles

Join a Firm as a Trainee Mortgage Adviser

Many firms recruit trainee advisers who receive additional coaching while developing practical experience.

These roles usually combine:

  • Learning company systems
  • Shadowing experienced advisers
  • Completing supervised client work
  • Building product knowledge

This route provides structured support while gradually introducing you to real client interactions.

Start in a Mortgage Administrator Role

Mortgage administrator jobs are one of the most common entry points into the industry.

Responsibilities often include:

  • Processing mortgage applications
  • Liaising with lenders
  • Preparing client paperwork
  • Managing case progress
  • Supporting qualified advisers

Although administration is different from giving advice, it provides valuable exposure to how the mortgage process works.

Many advisers begin in administration before progressing into advisory positions.

Common job searches include:

  • Mortgage administrator jobs
  • Mortgage admin jobs
  • Mortgage processing jobs
  • Mortgage case manager jobs
  • Mortgage support administrator

Work as a Mortgage Paraplanner or Case Handler

Some firms recruit mortgage case handlers or paraplanning support staff.

These positions help develop:

  • Technical knowledge
  • Lender requirements
  • Documentation processes
  • Compliance awareness

This experience can provide a solid foundation before moving into an adviser role.

Search terms include:

  • Mortgage case handler jobs
  • Mortgage case manager vacancies
  • Mortgage paraplanner jobs

Which Previous Careers Transfer Well?

Many successful advisers previously worked in customer-facing roles.

Examples include:

  • Retail management
  • Estate agency
  • Hospitality
  • Customer service
  • Teaching
  • Insurance
  • Recruitment
  • Banking
  • Sales
  • Public sector administration

These careers often develop communication, organisation and problem-solving skills that are highly relevant to mortgage advice.

Employers usually recognise that technical knowledge can be taught, while professionalism and interpersonal skills often take much longer to develop.

What Soft Skills Do Employers Look For?

Technical knowledge is only part of being an effective mortgage adviser.

Employers also value strong personal skills because advisers work closely with clients making significant financial decisions.

Communication

You’ll need to explain complex mortgage information in language clients understand.

Clear communication builds trust and helps clients make informed decisions.

Listening

Every client has different circumstances.

Good advisers spend as much time listening as they do talking.

Understanding a client’s goals is essential before recommending suitable solutions.

Organisation

Mortgage applications involve deadlines, documents and communication with multiple parties.

Strong organisational skills help keep applications progressing smoothly.

Attention to Detail

Small mistakes can delay applications or create unnecessary complications.

Checking information carefully is an important part of the role.

Empathy

Buying a home can be exciting but also stressful.

Clients often appreciate advisers who remain patient, calm and supportive throughout the process.

Professionalism

Mortgage advice is a regulated profession.

Professional behaviour, honesty and integrity are expected at every stage of your career.

What Should You Expect in Your First Mortgage Job?

Your first position is unlikely to involve immediately advising clients independently.

Most new advisers spend time learning:

  • Internal systems
  • Compliance procedures
  • Lender criteria
  • Company processes
  • Customer service standards
  • Regulatory expectations

If you’re joining as a trainee, you’ll often work under supervision while building confidence.

There is usually a gradual increase in responsibility rather than being expected to know everything from day one.

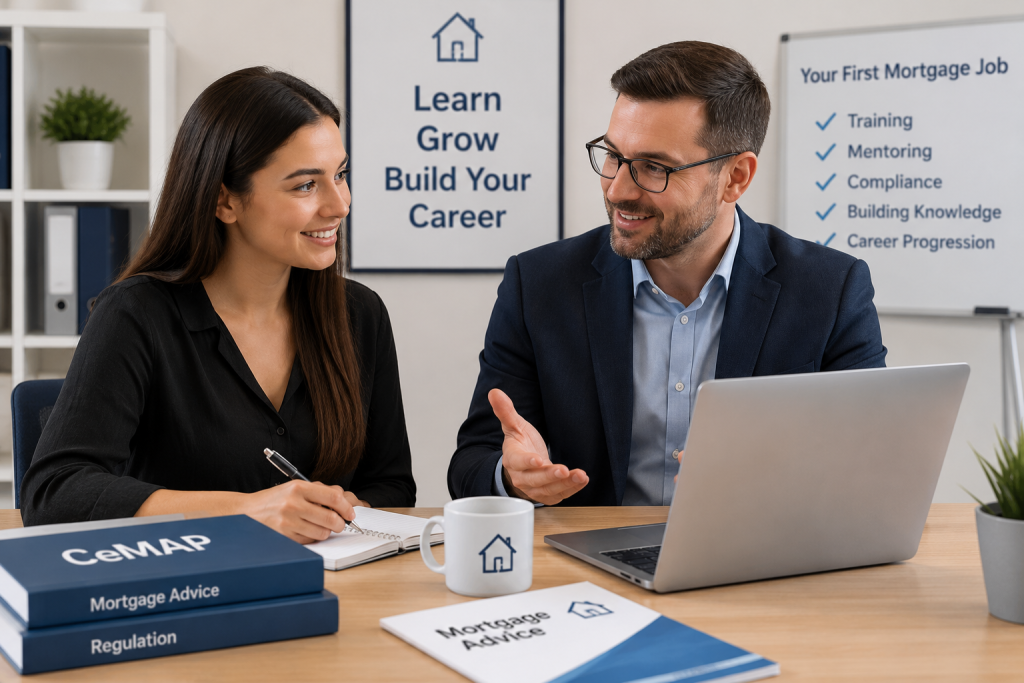
A trainee mortgage adviser receiving guidance from an experienced colleague in a modern office during their first mortgage job.

How Difficult Is It to Get Your First Mortgage Adviser Job?

Finding your first role can take time, particularly if you have no industry experience.

Competition varies depending on location and employer requirements.

Having CeMAP already completed can strengthen your application because it demonstrates commitment and reduces the amount of initial training required.

It’s also worth remembering that many successful advisers did not secure their first interview immediately.

Persistence, continued learning and applying for suitable entry-level positions often make a significant difference.

How Can You Make Your CV Stand Out?

If you have no mortgage experience, focus on your transferable strengths rather than what you lack.

Highlight examples of:

  • Customer service achievements
  • Sales experience
  • Problem solving
  • Handling confidential information
  • Meeting targets
  • Working under pressure
  • Administrative accuracy
  • Communication skills

If you’ve completed CeMAP, make this clearly visible near the top of your CV.

Employers should immediately recognise your qualification and commitment to entering the profession.

Where Should Beginners Look for Mortgage Industry Jobs?

When searching online, using a variety of job titles will help you find more opportunities.

Useful searches include:

  • Trainee mortgage adviser jobs
  • Junior mortgage adviser jobs
  • Mortgage administrator jobs
  • Mortgage case manager jobs
  • Mortgage case handler jobs
  • Mortgage processing jobs
  • Mortgage support administrator
  • Mortgage customer service adviser
  • Mortgage assistant jobs
  • CeMAP jobs
  • Financial services administrator
  • Mortgage broker trainee
  • Mortgage adviser graduate jobs (where applicable)

Many vacancies may not include the exact title “mortgage adviser”, especially for beginner roles.

Keeping your searches broad can uncover opportunities that lead into advisory careers.

Does Previous Financial Experience Give You an Advantage?

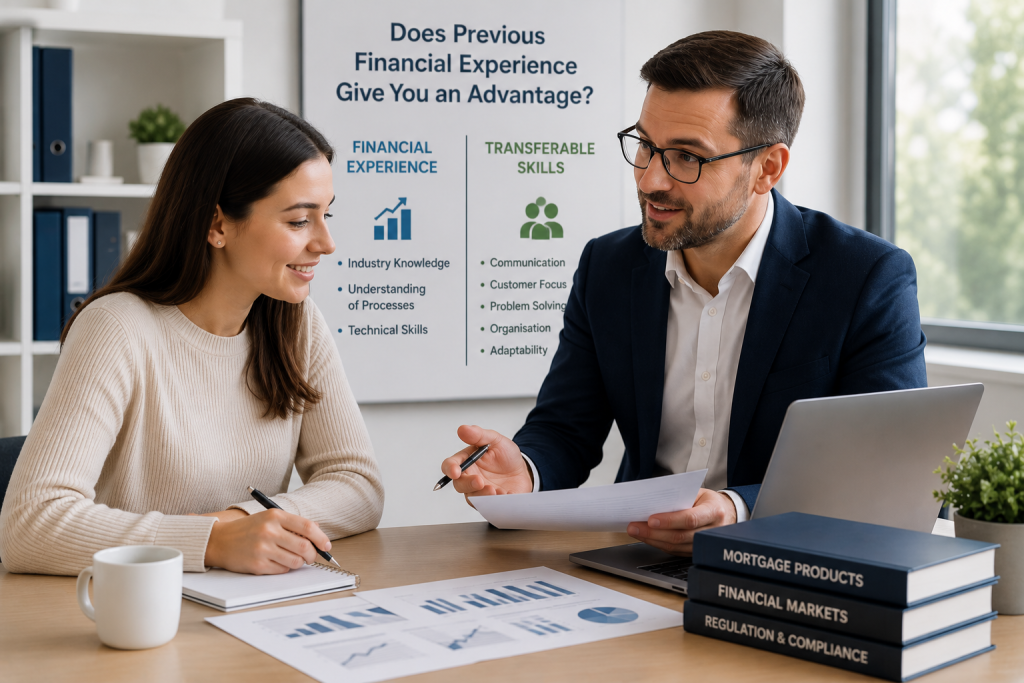
Previous financial services experience can certainly help, but it isn’t essential.

Someone who has worked in banking may already understand financial terminology or lending processes.

However, someone from retail may have stronger customer relationship skills.

Someone from teaching may communicate complex information particularly well.

Every background brings different strengths.

Employers often recruit people based on their potential, attitude and willingness to learn, rather than simply their previous industry.

An experienced mortgage professional mentoring a trainee in a modern office, showing that both financial experience and transferable skills are valuable for a mortgage adviser career.

Is Becoming a Mortgage Adviser a Good Career Change?

For many people, mortgage advice offers the opportunity to build a professional career while helping clients make important financial decisions.

The work combines technical knowledge with customer interaction, making it appealing to people who enjoy both learning and working with others.

Like any regulated profession, it requires ongoing professional development, keeping up to date with regulation and continuously expanding your knowledge.

Success rarely happens overnight, but those prepared to invest in learning and professional growth often find the career both rewarding and varied.

Final Thoughts

So, can you become a mortgage adviser with no experience?

Yes. Many people successfully enter the profession without previous financial services experience. The key is understanding that experience isn’t the only factor employers consider.

Completing CeMAP provides the educational foundation needed to begin your career, while transferable skills such as communication, organisation, professionalism and empathy often make a strong impression during recruitment.

Whether you begin as a trainee mortgage adviser, mortgage administrator or another entry-level role, each step helps build the knowledge and confidence needed to progress.

Rather than worrying about what experience you don’t have, focus on developing the qualifications, skills and mindset that employers value. With realistic expectations and a willingness to learn, a career in mortgage advice can be an achievable goal for people from many different backgrounds.

Looking for training support?

We offer CeMAP training for learners working towards a career in mortgage advice. Our courses follow the London Institute of Banking & Finance syllabus and are designed to support understanding of mortgage regulation and advice requirements.

Explore our accredited CeMAP training courses

> Futuretrend Financial Training