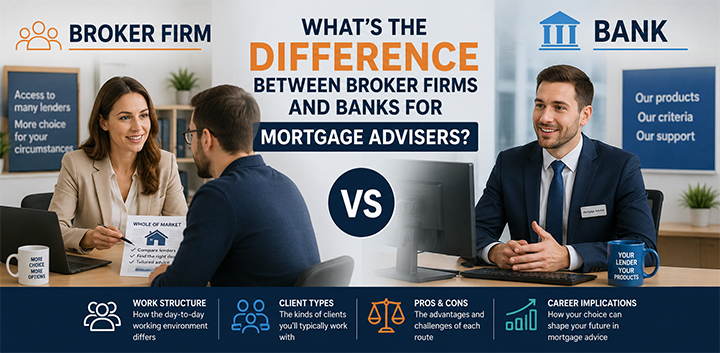
What’s the Difference Between Broker Firms and Banks for Mortgage Advisers?

Broker vs bank mortgage adviser comparison in the UK

If you are starting a career as a mortgage adviser, one of the decisions you may eventually face is whether to work for a mortgage broker firm or a bank or building society. Both can provide a route into mortgage advice, but the day-to-day working environment can be quite different.

The main difference is the range of mortgage products you are able to advise on and the way clients reach you. A mortgage adviser working for a bank or building society will generally advise on products available from that particular lender. An adviser working for a broker firm may have access to products from a wider range of lenders, although the exact scope will depend on the firm and its proposition.

Neither route is automatically better. For a new mortgage adviser, the right environment depends on the type of work you enjoy, the support you need and where you would like your career to develop.

Broker vs bank mortgage adviser comparison in the UK

What Is the Difference Between a Mortgage Broker and a Bank Mortgage Adviser?

A bank mortgage adviser works for a particular lender and advises customers within that lender’s mortgage proposition. Their role is usually part of a larger organisation with established processes, systems, targets and management structures.

A mortgage broker works within an intermediary business. Rather than representing one lender’s mortgage range, the broker researches suitable mortgage products from the lenders available through the firm’s panel or sourcing arrangements.

This creates an important difference in the role.

A bank adviser may become very familiar with one lender’s criteria, products and internal processes. A broker needs to understand how different lenders approach areas such as affordability, property types, employment circumstances and lending criteria.

In both environments, however, mortgage advice remains a regulated activity. Advisers need the appropriate knowledge and competence and must work within the regulatory framework applying to mortgage advice.

How Does the Work Structure Differ Between a Broker Firm and a Bank?

Banks and larger building societies often have a more structured working environment. There may be clearly defined processes covering appointments, compliance, training, supervision and progression.

For somebody entering mortgage advice for the first time, that structure can be useful. You may have a manager, experienced advisers and dedicated compliance or training teams around you.

Broker firms vary much more.

A large national brokerage may have a structure that feels similar to a bank, with centralised systems, training and management. A small independent brokerage could consist of only a handful of advisers and administrators.

That does not necessarily mean a smaller broker provides less support. In some firms, new advisers work closely with experienced brokers and receive considerable one-to-one guidance.

The important point for new entrants is that “broker” does not describe one particular working environment. When considering a role, look at the individual firm rather than making assumptions based purely on whether it is a bank or brokerage.

Do Mortgage Brokers and Bank Advisers Deal With Different Clients?

They can, although there is considerable overlap.

A bank mortgage adviser may speak to existing customers of the bank as well as people who have approached that lender specifically for a mortgage. Clients may arrive through branches, telephone enquiries, online applications or referrals within the organisation.

This means the adviser may spend less time generating their own leads because the organisation already has an established customer base.

A broker firm may receive clients through online enquiries, estate agents, existing customer referrals, professional connections or marketing activity. Depending on the business model, individual advisers may also be expected to develop relationships and generate new business.

Brokers can also encounter clients whose circumstances require them to consider different lenders.

For example, a straightforward employed applicant with a good deposit may potentially meet the criteria of numerous lenders. Someone who is self-employed, has unusual income arrangements or is buying a less conventional property may require more research.

That can make brokerage work varied, but it can also increase the amount of research involved.
Mortgage broker and bank adviser meeting different types of UK mortgage clients

Does a Mortgage Broker Have Access to More Lenders?

Generally, a broker firm can consider a broader range of lenders than an adviser employed by a single bank, but you should not assume that every broker has access to every mortgage available.

Broker firms can operate with different lender panels and product arrangements. Some may offer advice across a broad part of the market, while others may work with a more restricted panel.

A bank or building society adviser is different because their advice is centred on that organisation’s own mortgage proposition.

For somebody considering a career in mortgage advice, this affects the knowledge required.

Within a bank, you may develop detailed knowledge of that lender’s criteria and processes. Within a brokerage, you may need to become comfortable comparing different lenders and recognising where criteria vary.

What Are the Advantages of Working for a Bank as a Mortgage Adviser?

One potential advantage is structure.

Larger financial organisations commonly have established training programmes, management structures, technology, compliance processes and defined responsibilities. This can provide a relatively clear environment in which to learn.

Other possible advantages include:

  • an existing flow of customers and enquiries
  • clearly defined procedures and processes
  • access to internal training and support
  • established compliance and supervision structures
  • potential opportunities to move into other roles within a larger organisation

There can be disadvantages as well.

Your product range will generally be limited to the lender you work for, and larger organisations can have more rigid procedures. Targets and performance measures may also form a significant part of the working environment.

Someone who enjoys clearly defined processes may find that structure helpful. Someone looking for greater independence or a broader range of mortgage cases may eventually prefer another environment.

What Are the Advantages of Working for a Mortgage Broker Firm?

Brokerage can provide exposure to a wider range of lenders, criteria and client circumstances.

That variety can help an adviser build broad mortgage knowledge over time. Instead of asking whether a customer fits one lender’s criteria, the research process may involve identifying which available lender is appropriate for that customer’s circumstances.

Depending on the firm, potential advantages can include:

  • exposure to multiple lenders
  • varied client circumstances
  • broader experience of mortgage criteria
  • opportunities to develop client relationships
  • potential routes towards more independent or self-employed work later in your career

There are also possible disadvantages.

The amount of support varies considerably between firms. Some roles may involve greater responsibility for generating business, managing a pipeline or maintaining professional referral relationships.

Smaller businesses may also have fewer formal career levels than a major bank.

For a new entrant, the name of the role therefore tells you less than the actual support structure behind it.

Is It Easier to Start Your Mortgage Adviser Career in a Bank or Broker Firm?

There is no single best starting point.

A bank may suit someone who wants a highly structured introduction to financial services. A broker firm may suit someone who wants early exposure to different lenders and a wider variety of mortgage cases.

However, the quality of the individual employer is more important than choosing “bank” or “broker” in isolation.

When comparing entry-level mortgage adviser jobs, look at how the employer supports somebody who is newly qualified or still developing competence.

Useful questions include whether you will have a dedicated supervisor, how cases are checked, what training is provided, how leads are generated and what is expected of you during your first few months.

A supportive broker firm may be a much better starting environment than a poorly supported role at a larger organisation, and the reverse can also be true.
New mortgage adviser considering whether to start a career with a bank or broker firm

How Could Your Choice Affect Your Mortgage Adviser Career?

Your first employer does not determine your entire career.

Mortgage advisers can move between banks, building societies, broker firms and other intermediary businesses as their experience develops.

Someone who begins with a bank may build strong experience in client conversations, regulated processes and mortgage applications before moving into brokerage.

Someone starting with a broker may develop broader knowledge of lender criteria and later decide to specialise, move to a larger firm or eventually explore self-employment.

There are also career routes beyond directly advising clients, including compliance, training, management, specialist mortgage advice and business development.

This is why your first mortgage adviser role should be viewed as a place to build practical competence, rather than a permanent choice between two sides of the industry.

Broker vs Bank Mortgage Adviser: Which Is Better?

Neither a broker firm nor a bank is inherently the better place to work as a mortgage adviser.

Banks and building societies can offer a more structured environment with established processes and an existing customer base, while broker firms can provide greater exposure to different lenders, mortgage criteria and client circumstances.

For someone entering the profession, factors such as training, supervision, workplace culture, lead generation and opportunities to gain experience are often more useful considerations than the type of organisation alone.

CeMAP provides the underpinning knowledge needed for a mortgage advice career, but becoming an effective adviser also requires practical development. Your first role is where much of that transition from learning mortgage advice to applying it with real clients begins.

Choosing between a broker and a bank is therefore less about finding the universally “best” option and more about finding the environment in which you can develop the skills, experience and confidence needed for the direction you want your mortgage career to take.

Looking for training support?

We offer CeMAP training for learners working towards a career in mortgage advice. Our courses follow the London Institute of Banking & Finance syllabus and are designed to support understanding of mortgage regulation and advice requirements.

Explore our accredited CeMAP training courses

> Futuretrend Financial Training 
What Does a Trainee Mortgage Adviser Role Involve?

Trainee mortgage adviser learning from an experienced adviser in their first mortgage advice role

A trainee mortgage adviser role is usually the first step between gaining mortgage knowledge and becoming confident enough to advise clients in a real working environment. The role combines further learning with practical experience, supervised client work, administration and an increasing understanding of how the mortgage process works from enquiry through to completion.

For someone starting their first job in mortgage advice, the experience can feel quite different from studying CeMAP. Passing CeMAP exams gives you important knowledge, but a trainee role is where you begin learning how to apply that knowledge to real customers, real lender criteria and real cases.

The exact role varies between employers. Some trainees begin with administration or observation before gradually taking on client conversations. Others work within structured academies or development programmes. You should therefore expect a learning curve rather than assuming you will immediately spend every day giving mortgage advice.

Trainee mortgage adviser learning from an experienced adviser in their first mortgage advice role

What Does a Trainee Mortgage Adviser Do?

A trainee mortgage adviser learns how to apply mortgage knowledge within a regulated working environment while developing the practical skills needed to deal with clients and mortgage applications.

Depending on the employer and your stage of development, this could include observing experienced advisers, speaking with clients, gathering information, completing fact-finds, researching mortgage options, maintaining client records and helping applications progress.

Your responsibilities are likely to increase as you demonstrate that you can complete tasks accurately and follow the organisation’s processes.

It is important to distinguish this from simply passing CeMAP. The qualification provides the knowledge required for mortgage advice, but employers will normally have their own processes for training, supervision and assessing whether a new adviser is ready to undertake different activities.

What Does a Typical Day Look Like for a Trainee Mortgage Adviser?

There is not one standard working day because mortgage adviser roles vary considerably between banks, building societies, brokerages and other mortgage businesses.

However, a trainee might spend time on activities such as:

  • reviewing new mortgage enquiries and existing cases
  • contacting clients for information or documents
  • observing or participating in client appointments
  • completing or updating fact-finds
  • researching lender products and criteria
  • preparing case information for review
  • updating customer records and internal systems
  • speaking with lenders or other parties about applications
  • completing training and development activities
  • discussing cases with a supervisor or experienced adviser
  • following up outstanding information.

Some days may be heavily focused on clients, while others involve more administration, research or training.

This is one reason new advisers sometimes find the transition from CeMAP study surprising. Mortgage advice is not simply a matter of knowing which mortgage product looks suitable. A considerable amount of work can go into understanding a client’s circumstances, documenting the advice and progressing an application.

Will You Give Mortgage Advice Straight Away?

Not necessarily.

Having CeMAP does not automatically mean an employer will expect you to begin handling complete mortgage cases independently from your first day.

A new adviser needs to understand the organisation’s systems, procedures, compliance requirements, lender relationships and approach to dealing with clients. Employers may also have their own competency requirements before allowing someone to undertake particular activities without close supervision.

You might therefore begin by observing appointments, completing sections of the process or working alongside a more experienced colleague.

As your knowledge and practical ability develop, you may be given greater responsibility.

This gradual progression is useful. A classroom or home-study example can be designed to test a particular area of knowledge. Real customers rarely arrive with circumstances that fit neatly into a textbook example.

What Is the Learning Curve Like in Your First Mortgage Adviser Job?

The learning curve can be significant because you are learning a job as well as applying your mortgage knowledge.

CeMAP helps you understand areas such as mortgage products, regulation and the principles surrounding suitable advice. Your first role introduces another layer: how those principles work when dealing with an actual client.

For example, you may need to learn how to:

  • ask questions naturally rather than simply reading through a fact-find
  • identify when additional information is needed
  • explain mortgage terminology clearly
  • research lender criteria efficiently
  • use mortgage sourcing and customer management systems
  • keep accurate case notes
  • manage several applications at different stages
  • communicate with clients when something changes.

You are also likely to encounter situations you have never previously studied as a straightforward example.

That does not make your CeMAP knowledge irrelevant. It becomes the foundation on which your practical experience is built.

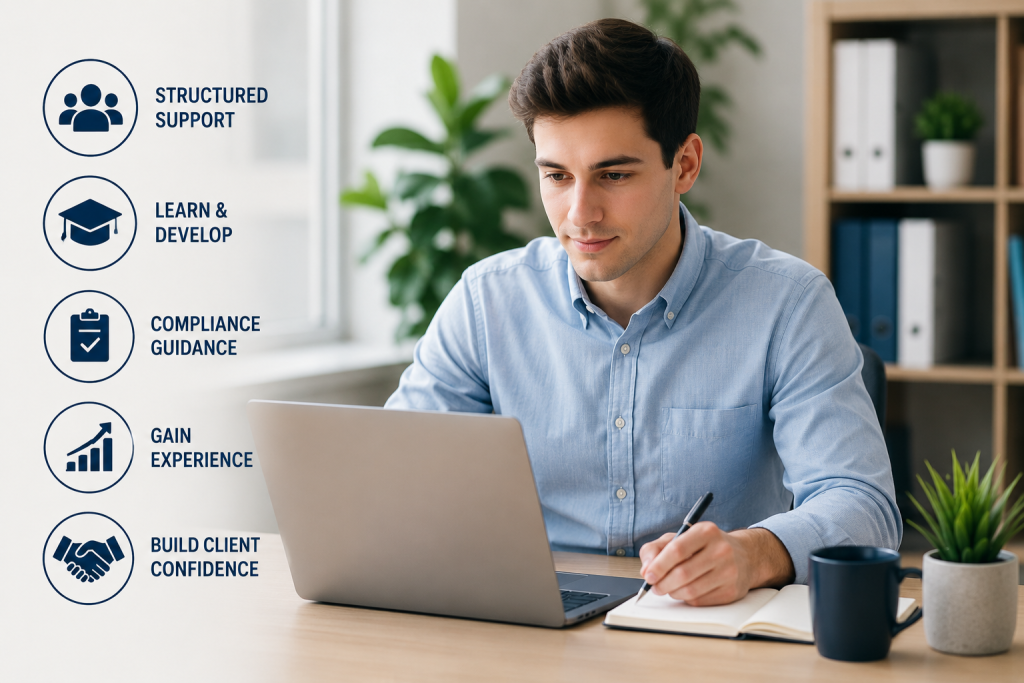
Trainee mortgage adviser developing skills through learning, practice, support and experience

What Support Should a Trainee Mortgage Adviser Receive?

Support structures differ between employers, but trainees would normally expect some form of supervision and development while learning the role.

This could involve working with a manager, supervisor, mentor, trainer or experienced mortgage adviser. Some larger organisations have formal training programmes, while smaller brokerages may provide more direct one-to-one development.

Support might include observing appointments, reviewing completed work, discussing cases, receiving feedback and having someone available when you are unsure how to proceed.

An important part of being a trainee is knowing when to ask for help.

Trying to appear more experienced than you are can create problems. Mortgage cases can involve complex circumstances, and recognising that something needs checking is a valuable professional habit.

The aim is not to know everything immediately. It is to develop the judgement needed to recognise what you know, what you need to check and when a case needs additional support.

What Will an Employer Expect From a Trainee Mortgage Adviser?

Employers are unlikely to expect a trainee to have the knowledge and speed of an experienced adviser. They can, however, reasonably expect professionalism, accuracy and a willingness to learn.

Attention to detail matters particularly because mortgage applications involve financial information, documentation and regulated processes.

Organisation is also important. Once you are dealing with several clients, you need to know which cases require action, which documents are outstanding and when someone needs to be contacted.

Communication matters just as much. Clients may not understand mortgage terminology, and some may be nervous about borrowing a substantial amount of money. A good adviser needs to listen carefully and explain information in a way the client can understand.

Employers may therefore look beyond exam results when assessing a trainee. Your ability to communicate, organise your workload, follow procedures and respond constructively to feedback can all influence how quickly you develop.

Trainee mortgage adviser receiving guidance and feedback from an experienced colleague

How Much Administration Does a Trainee Mortgage Adviser Do?

Potentially quite a lot.

People considering mortgage advice sometimes picture the role mainly as sitting with clients and recommending mortgages. Client advice is important, but administration and case management are substantial parts of many mortgage roles.

Information needs to be gathered and recorded. Documents may need checking. Applications have to be submitted and monitored. Clients need updates, and additional information may be requested as a case progresses.

Accurate records are particularly important within financial services.

For trainees, administration can also be useful because it helps you understand the complete journey of a mortgage application rather than seeing only the advice conversation.

Over time, some workplaces may provide administrative or case-management support to advisers. Others expect advisers to remain closely involved throughout the process.

Is Working With Real Clients Different From CeMAP Study?

Yes. This is one of the biggest adjustments when entering your first mortgage adviser role.

Exam questions provide the information you need to reach an answer. Clients do not.

A client might forget something important, misunderstand a question or be unsure about their own financial arrangements. You may need to ask additional questions before you have enough information to understand their circumstances properly.

There is also a human element that cannot be fully replicated through exam study.

You might deal with first-time buyers who are nervous about the process, homeowners whose previous purchase was many years ago or clients frustrated because a lender has requested additional documents.

Being able to manage those conversations calmly is part of becoming an effective adviser.

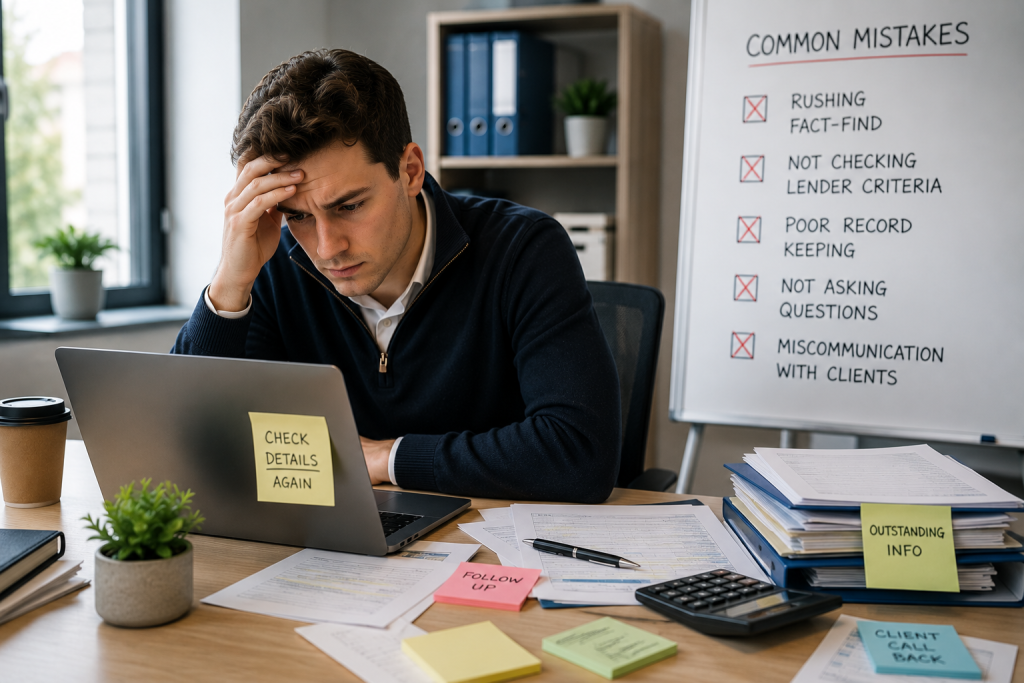
What Mistakes Do New Trainee Mortgage Advisers Commonly Make?

One common mistake is thinking that passing CeMAP means the learning has finished. In practice, it is much closer to the beginning of your professional development.

Another is trying to work too quickly.

Experienced advisers may recognise common situations and know where to research unusual ones. A trainee has not yet built that experience, so attempting to match an experienced colleague’s speed can lead to missed details.

Other early mistakes can include relying too heavily on mortgage sourcing results without checking criteria, using technical language with clients, allowing administration to build up or being reluctant to ask questions.

Feedback is therefore an important part of a trainee role. You will probably have work corrected at some point. The useful question is not whether you made a mistake, but whether you understand why it happened and can avoid repeating it.

Trainee mortgage adviser reviewing casework and learning from common mistakes

How Long Does It Take to Feel Confident as a Mortgage Adviser?

There is no fixed timescale.

Confidence develops through a combination of knowledge, repetition, feedback and exposure to different client situations. The amount of support available and the types of cases you encounter can also affect how quickly you progress.

Your first few client conversations may require considerable preparation. Tasks that initially take a long time can gradually become more familiar as you gain experience.

It is important not to confuse confidence with competence. Feeling comfortable speaking to clients is useful, but good mortgage advice also requires careful research, accurate records and an understanding of your responsibilities.

A trainee who checks something when uncertain may be demonstrating better judgement than someone who confidently guesses.

Is a Trainee Mortgage Adviser Role a Good Way to Start Your Career?

For someone who wants to become a mortgage adviser, a trainee position can provide the practical experience needed to turn CeMAP knowledge into professional capability.

It is not simply an extended training course. You are entering a working financial services environment where clients, deadlines, administration and regulatory responsibilities all matter.

There may be repetitive tasks. Applications can be delayed. Clients can be difficult to contact. Lender criteria can create complications, and some cases will require considerably more work than others.

That is part of the real role.

At the same time, each case gives you experience that cannot be gained solely from study materials. You begin to recognise different client circumstances, become more comfortable asking questions and learn how mortgage applications progress in practice.

The goal of your first trainee mortgage adviser role is not to know everything from day one. It is to build on your CeMAP knowledge, learn from experienced people around you and gradually become capable of handling mortgage cases with greater confidence and responsibility.

Looking for training support?

We offer CeMAP training for learners working towards a career in mortgage advice. Our courses follow the London Institute of Banking & Finance syllabus and are designed to support understanding of mortgage regulation and advice requirements.

Explore our accredited CeMAP training courses

> Futuretrend Financial Training 
Can You Become a Mortgage Adviser With No Experience?

Person studying CeMAP qualification at a desk with a laptop, representing how to become a mortgage adviser with no previous experience.

Changing careers can feel daunting, especially if you’re moving into a regulated profession like mortgage advice. Many people assume you need years of banking experience or a financial services background before you can even get started. In reality, that’s not the case.

The UK mortgage industry welcomes people from a wide range of professional backgrounds. While experience can certainly help, it is not a requirement for beginning your journey. What matters more is gaining the right qualification, developing the right skills and understanding what employers expect from someone entering the profession.

If you’re asking, “Can I become a mortgage adviser with no experience?“, the answer is yes, but you’ll need to approach it with realistic expectations. Becoming qualified is only one part of the journey. Building confidence, gaining industry knowledge and securing your first role all take time and commitment.

Person studying CeMAP qualification at a desk with a laptop, representing how to become a mortgage adviser with no previous experience.

Can You Become a Mortgage Adviser With No Experience?

Yes. Many mortgage advisers begin their careers without previous experience in financial services.

The profession attracts career changers from retail, hospitality, customer service, administration, teaching, sales and many other industries. These careers often develop valuable transferable skills that employers appreciate.

Experience alone does not qualify someone to provide mortgage advice.

Instead, aspiring advisers normally begin by obtaining the Certificate in Mortgage Advice and Practice (CeMAP) before looking for entry-level opportunities where they can continue developing professionally.

The important thing to understand is that employers are usually looking at your overall potential rather than simply your previous job title.

What Is CeMAP and Why Is It Important?

The Certificate in Mortgage Advice and Practice (CeMAP) is the industry standard qualification for mortgage advisers in the UK. It is awarded by the London Institute of Banking & Finance (LIBF) and meets the Financial Conduct Authority (FCA) education requirements for giving regulated mortgage advice.

For someone with no experience, CeMAP demonstrates several important qualities:

  • Commitment to entering the profession
  • Understanding of mortgage regulation
  • Knowledge of mortgage products and processes
  • Willingness to learn a regulated industry

While passing CeMAP does not guarantee employment, it significantly improves your opportunities because employers know you’ve already invested in learning the foundations of mortgage advice.

Many firms prefer recruiting qualified candidates because they require less initial technical training.

Study desk with mortgage books, laptop, notebook and a model house representing the CeMAP qualification and preparation for a mortgage adviser career.

What Entry Routes Are Available?

There is no single path into mortgage advice.

Depending on your circumstances, you might begin in several different ways.

Train First, Then Apply

Many career changers complete CeMAP before applying for jobs.

This approach allows you to focus on learning first and gives employers confidence that you’re serious about entering the profession.

Typical searches include:

  • CeMAP jobs
  • Trainee mortgage adviser jobs
  • Mortgage adviser jobs for beginners
  • Junior mortgage adviser roles

Join a Firm as a Trainee Mortgage Adviser

Many firms recruit trainee advisers who receive additional coaching while developing practical experience.

These roles usually combine:

  • Learning company systems
  • Shadowing experienced advisers
  • Completing supervised client work
  • Building product knowledge

This route provides structured support while gradually introducing you to real client interactions.

Start in a Mortgage Administrator Role

Mortgage administrator jobs are one of the most common entry points into the industry.

Responsibilities often include:

  • Processing mortgage applications
  • Liaising with lenders
  • Preparing client paperwork
  • Managing case progress
  • Supporting qualified advisers

Although administration is different from giving advice, it provides valuable exposure to how the mortgage process works.

Many advisers begin in administration before progressing into advisory positions.

Common job searches include:

  • Mortgage administrator jobs
  • Mortgage admin jobs
  • Mortgage processing jobs
  • Mortgage case manager jobs
  • Mortgage support administrator

Work as a Mortgage Paraplanner or Case Handler

Some firms recruit mortgage case handlers or paraplanning support staff.

These positions help develop:

  • Technical knowledge
  • Lender requirements
  • Documentation processes
  • Compliance awareness

This experience can provide a solid foundation before moving into an adviser role.

Search terms include:

  • Mortgage case handler jobs
  • Mortgage case manager vacancies
  • Mortgage paraplanner jobs

Which Previous Careers Transfer Well?

Many successful advisers previously worked in customer-facing roles.

Examples include:

  • Retail management
  • Estate agency
  • Hospitality
  • Customer service
  • Teaching
  • Insurance
  • Recruitment
  • Banking
  • Sales
  • Public sector administration

These careers often develop communication, organisation and problem-solving skills that are highly relevant to mortgage advice.

Employers usually recognise that technical knowledge can be taught, while professionalism and interpersonal skills often take much longer to develop.

What Soft Skills Do Employers Look For?

Technical knowledge is only part of being an effective mortgage adviser.

Employers also value strong personal skills because advisers work closely with clients making significant financial decisions.

Communication

You’ll need to explain complex mortgage information in language clients understand.

Clear communication builds trust and helps clients make informed decisions.

Listening

Every client has different circumstances.

Good advisers spend as much time listening as they do talking.

Understanding a client’s goals is essential before recommending suitable solutions.

Organisation

Mortgage applications involve deadlines, documents and communication with multiple parties.

Strong organisational skills help keep applications progressing smoothly.

Attention to Detail

Small mistakes can delay applications or create unnecessary complications.

Checking information carefully is an important part of the role.

Empathy

Buying a home can be exciting but also stressful.

Clients often appreciate advisers who remain patient, calm and supportive throughout the process.

Professionalism

Mortgage advice is a regulated profession.

Professional behaviour, honesty and integrity are expected at every stage of your career.

What Should You Expect in Your First Mortgage Job?

Your first position is unlikely to involve immediately advising clients independently.

Most new advisers spend time learning:

  • Internal systems
  • Compliance procedures
  • Lender criteria
  • Company processes
  • Customer service standards
  • Regulatory expectations

If you’re joining as a trainee, you’ll often work under supervision while building confidence.

There is usually a gradual increase in responsibility rather than being expected to know everything from day one.

A trainee mortgage adviser receiving guidance from an experienced colleague in a modern office during their first mortgage job.

How Difficult Is It to Get Your First Mortgage Adviser Job?

Finding your first role can take time, particularly if you have no industry experience.

Competition varies depending on location and employer requirements.

Having CeMAP already completed can strengthen your application because it demonstrates commitment and reduces the amount of initial training required.

It’s also worth remembering that many successful advisers did not secure their first interview immediately.

Persistence, continued learning and applying for suitable entry-level positions often make a significant difference.

How Can You Make Your CV Stand Out?

If you have no mortgage experience, focus on your transferable strengths rather than what you lack.

Highlight examples of:

  • Customer service achievements
  • Sales experience
  • Problem solving
  • Handling confidential information
  • Meeting targets
  • Working under pressure
  • Administrative accuracy
  • Communication skills

If you’ve completed CeMAP, make this clearly visible near the top of your CV.

Employers should immediately recognise your qualification and commitment to entering the profession.

Where Should Beginners Look for Mortgage Industry Jobs?

When searching online, using a variety of job titles will help you find more opportunities.

Useful searches include:

  • Trainee mortgage adviser jobs
  • Junior mortgage adviser jobs
  • Mortgage administrator jobs
  • Mortgage case manager jobs
  • Mortgage case handler jobs
  • Mortgage processing jobs
  • Mortgage support administrator
  • Mortgage customer service adviser
  • Mortgage assistant jobs
  • CeMAP jobs
  • Financial services administrator
  • Mortgage broker trainee
  • Mortgage adviser graduate jobs (where applicable)

Many vacancies may not include the exact title “mortgage adviser”, especially for beginner roles.

Keeping your searches broad can uncover opportunities that lead into advisory careers.

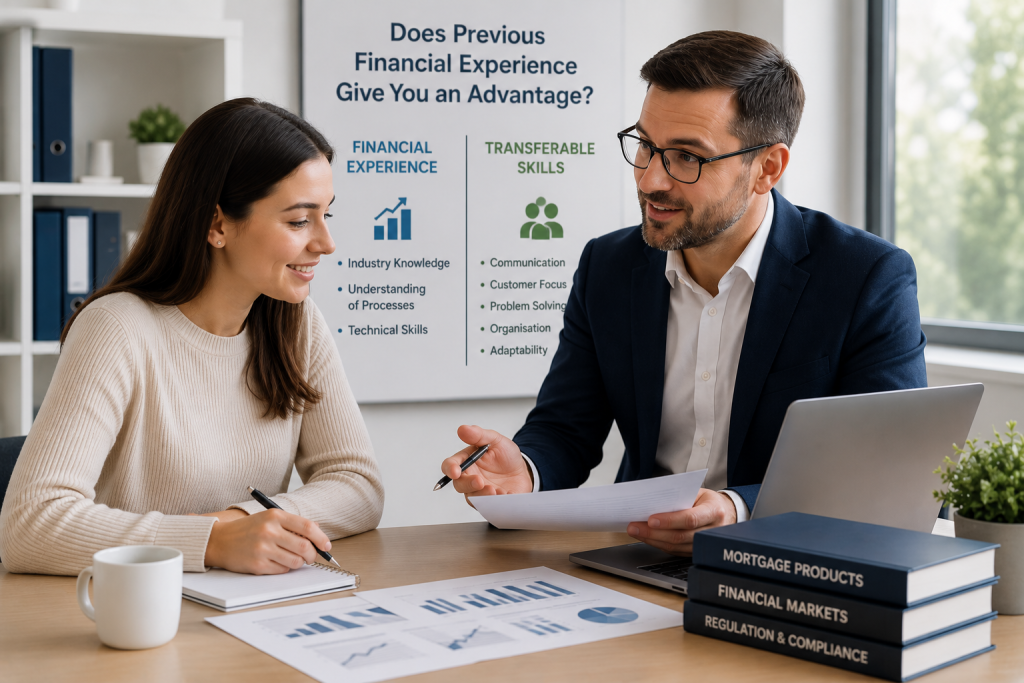
Does Previous Financial Experience Give You an Advantage?

Previous financial services experience can certainly help, but it isn’t essential.

Someone who has worked in banking may already understand financial terminology or lending processes.

However, someone from retail may have stronger customer relationship skills.

Someone from teaching may communicate complex information particularly well.

Every background brings different strengths.

Employers often recruit people based on their potential, attitude and willingness to learn, rather than simply their previous industry.

An experienced mortgage professional mentoring a trainee in a modern office, showing that both financial experience and transferable skills are valuable for a mortgage adviser career.

Is Becoming a Mortgage Adviser a Good Career Change?

For many people, mortgage advice offers the opportunity to build a professional career while helping clients make important financial decisions.

The work combines technical knowledge with customer interaction, making it appealing to people who enjoy both learning and working with others.

Like any regulated profession, it requires ongoing professional development, keeping up to date with regulation and continuously expanding your knowledge.

Success rarely happens overnight, but those prepared to invest in learning and professional growth often find the career both rewarding and varied.

Final Thoughts

So, can you become a mortgage adviser with no experience?

Yes. Many people successfully enter the profession without previous financial services experience. The key is understanding that experience isn’t the only factor employers consider.

Completing CeMAP provides the educational foundation needed to begin your career, while transferable skills such as communication, organisation, professionalism and empathy often make a strong impression during recruitment.

Whether you begin as a trainee mortgage adviser, mortgage administrator or another entry-level role, each step helps build the knowledge and confidence needed to progress.

Rather than worrying about what experience you don’t have, focus on developing the qualifications, skills and mindset that employers value. With realistic expectations and a willingness to learn, a career in mortgage advice can be an achievable goal for people from many different backgrounds.

Looking for training support?

We offer CeMAP training for learners working towards a career in mortgage advice. Our courses follow the London Institute of Banking & Finance syllabus and are designed to support understanding of mortgage regulation and advice requirements.

Explore our accredited CeMAP training courses

> Futuretrend Financial Training 
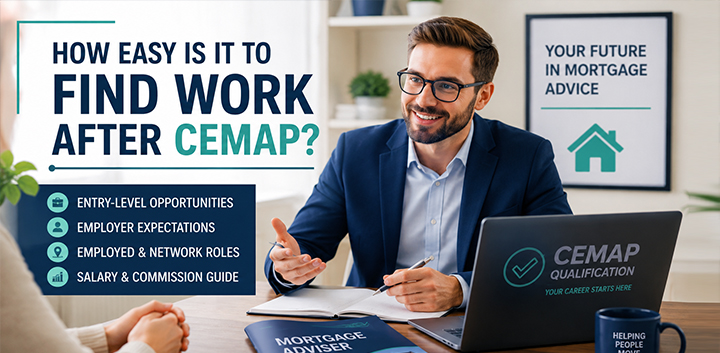
How Easy Is It to Find Work After CeMAP?

Newly qualified CeMAP learner discussing mortgage adviser career opportunities with a client in a professional office environment.

Many people start studying CeMAP because they want a new career as a mortgage adviser. One of the most common questions learners ask is simple: can you get a job after CeMAP?

The short answer is yes. CeMAP is the industry-standard mortgage advice qualification in the UK and meets the Financial Conduct Authority (FCA) education requirements for giving regulated mortgage advice. However, passing CeMAP is only one part of becoming a successful mortgage adviser. Finding work depends on a combination of qualifications, experience, employer expectations, location, and the type of role you are pursuing.

For most learners, CeMAP opens the door to opportunities rather than guaranteeing employment. Understanding what employers look for and the different routes available can help you set realistic expectations and plan your next steps.

Newly qualified CeMAP learner discussing mortgage adviser career opportunities with a client in a professional office environment.

Can You Get a Job After CeMAP?

Yes, many people secure mortgage-related roles after completing CeMAP.

Across the UK there are regularly vacancies for trainee mortgage advisers, trainee mortgage brokers, mortgage and protection advisers, adviser support staff, and other entry-level positions that either require CeMAP or actively support newly qualified candidates.

CeMAP is designed to provide the knowledge needed to begin advising on mortgages within a regulated environment. It demonstrates to employers that you understand mortgage regulation, products, the house-buying process, and the responsibilities involved in providing advice.

However, most employers recognise that newly qualified advisers still need practical experience and supervision before they become fully established advisers.

This means that the first role after CeMAP is often focused on development, training, mentoring, and building real-world experience.

What Entry-Level Opportunities Are Available After CeMAP?

A newly qualified CeMAP learner may find opportunities in several areas.

Trainee Mortgage Adviser Roles

Many firms recruit trainee mortgage advisers and provide structured support to help new advisers develop their skills. These roles typically combine learning, supervision, and client interaction. Trainee vacancies are advertised regularly across the UK by broker firms, estate agency groups, mortgage networks, and specialist advice businesses.

Mortgage Administrator or Case Manager Roles

Some learners choose to start in an administrative or case management position.

These roles involve supporting advisers with applications, documentation, lender communication, and client updates. They provide valuable exposure to the mortgage process and can be a useful stepping stone towards a full advisory role.

Banking and Financial Services Positions

Banks, building societies, and financial services firms often value CeMAP as evidence of industry knowledge. While not every role involves mortgage advice immediately, experience gained within financial services can help build a long-term advisory career.

Apprenticeships and Employer-Sponsored Development

Some employers recruit individuals into training programmes that include adviser development and supervised learning. These schemes can offer a structured route into the profession while building experience alongside qualifications.

Why Does Experience Matter After CeMAP?

One of the biggest concerns for newly qualified learners is the lack of experience.

This is understandable because most people studying CeMAP are changing careers or entering financial services for the first time.

Employers know that qualifications and experience are different things.

CeMAP teaches the knowledge required to understand mortgages and regulation. Experience develops skills such as:

  • Conducting client fact-finds
  • Identifying suitable mortgage solutions
  • Explaining recommendations clearly
  • Managing client expectations
  • Handling complex cases
  • Maintaining compliant records

These skills are usually developed through supervised practice and on-the-job learning rather than through examinations alone.

This is why many employers focus on attitude, communication skills, professionalism, and willingness to learn when recruiting newly qualified advisers.

newly-qualified-mortgage-adviser-starting-career

What Do Employers Look for Beyond CeMAP?

Holding CeMAP is important, but employers often assess much more than qualifications.

Strong Communication Skills

Mortgage advisers spend much of their time speaking with clients.

Employers want advisers who can explain complex information clearly, build trust, and communicate professionally.

Customer Service Experience

Many successful mortgage advisers previously worked in customer-facing roles such as retail, banking, estate agency, hospitality, or sales.

Experience dealing with customers can often be as valuable as industry experience when applying for trainee positions.

Organisation and Attention to Detail

Mortgage advice involves significant documentation and regulatory responsibilities.

Employers value candidates who can manage workloads, maintain records accurately, and work within established processes.

Professionalism and Motivation

A mortgage advice career requires continuous learning and development.

Many employers look for candidates who demonstrate commitment, resilience, and a genuine interest in helping clients.

Do Different Regions Have Different Opportunities?

Yes, opportunities can vary significantly across the UK.

Large cities and densely populated areas often have a greater number of mortgage firms, estate agency chains, brokerages, and financial services businesses. This can create more opportunities for newly qualified advisers.

However, regional markets can also offer advantages.

Smaller firms may provide closer mentoring and broader exposure to different types of mortgage cases. Some employers actively recruit locally and value candidates who understand their community and customer base.

Remote and hybrid advisory roles have also become more common, meaning location is not always the barrier it once was.

The key point is that employability often depends more on the individual employer and role than on geography alone.

What Is the Difference Between an Employed Adviser and a Network Adviser?

Many learners are surprised to discover that there are different ways to work as a mortgage adviser.

The two most common models are employed positions and network-based positions.

Employed Mortgage Adviser Roles

An employed adviser works directly for a company and receives a salary.

These roles often include:

  • Basic salary
  • Commission or performance bonuses
  • Structured training
  • Compliance support
  • Existing lead sources
  • Employee benefits

Many newly qualified advisers begin in employed positions because they provide stability and structured development. Numerous trainee adviser vacancies advertise a salary plus commission model, helping advisers gain experience while building confidence.

Network and Appointed Representative Roles

Mortgage networks allow advisers to operate under the regulatory umbrella of an authorised firm.

Under the FCA framework, advisers can become appointed representatives (ARs) of authorised firms rather than seeking direct authorisation themselves.

Networks typically provide:

  • Compliance oversight
  • Lender access
  • Training and development
  • Systems and technology
  • Ongoing support

Some network roles are employed positions, while others are self-employed arrangements.

Many networks also provide mentoring and development opportunities for newly qualified advisers working towards Competent Adviser Status (CAS).

How Does Pay Usually Work in Network Positions?

Network-based roles can vary significantly.

Some advisers receive a basic salary plus commission. Others operate on a self-employed basis and earn through commission generated from completed business.

The exact structure depends on the network, the appointed representative firm, lead generation arrangements, and individual contracts.

Newly qualified advisers should understand that self-employed or commission-based roles often require greater responsibility for business generation and client acquisition. Some firms provide leads and marketing support, while others expect advisers to develop their own referral relationships and client pipeline.

Neither model is automatically better.

The most suitable option depends on experience level, confidence, support requirements, and personal career goals.

Do Newly Qualified Advisers Need Competent Adviser Status (CAS)?

In many advisory environments, newly qualified advisers work under supervision before achieving Competent Adviser Status (CAS).

CAS is an employer or firm assessment that demonstrates an adviser can provide advice independently within that organisation’s standards and processes.

Achieving CeMAP does not automatically grant CAS.

Instead, advisers usually gain practical experience, complete supervised cases, receive mentoring, and demonstrate competence before being signed off by their employer or network.

This development period is a normal part of the profession and should be viewed as a learning opportunity rather than an obstacle.

newly-qualified-mortgage-adviser-starting-career

What Can Improve Your Chances of Finding Work After CeMAP?

Several practical steps can improve employability after qualification.

Gain Relevant Experience

Customer service, banking, estate agency, financial services, and sales experience can all strengthen applications.

Build Industry Knowledge

Following mortgage market developments, lender criteria, and regulatory updates can help during interviews.

Apply Broadly

Many learners focus only on adviser positions.

Considering trainee roles, administration positions, case manager opportunities, and support roles can increase the number of potential entry points.

Demonstrate Commitment

Employers value candidates who show enthusiasm for the profession and understand the responsibilities involved in regulated advice.

Be Open to Development

The first role may not be the final destination.

Many successful advisers started in support or trainee positions before progressing into fully established advisory careers.

Is It Easy to Find Work After CeMAP?

The honest answer is that it depends on the individual circumstances.

CeMAP is a respected qualification that creates opportunities, but employers also consider experience, communication skills, professionalism, and cultural fit.

For some learners, a position may come quickly. Others may need to build experience through trainee roles or support positions before moving into a full advisory role.

What is important is recognising that CeMAP is designed to help you enter the profession, not instantly complete the journey.

Final Thoughts

Can you get a job after CeMAP?

Yes. Many employers across the mortgage and financial services sector recruit CeMAP-qualified candidates, including those with little or no direct mortgage experience. Trainee adviser roles, support positions, employed adviser opportunities, and network-based pathways all exist within the industry.

However, CeMAP should be viewed as the starting point rather than the finish line.

Employers typically look for a combination of qualifications, practical skills, professionalism, and willingness to learn. The strongest candidates are often those who understand that building a successful mortgage advice career involves continued development, gaining experience, and gradually building confidence within a regulated profession.

For learners considering CeMAP, that should be encouraging. Passing the qualification can open the door to a range of career opportunities, even if the first step into the industry is not always the same for everyone.

This article follows current CeMAP qualification and mortgage adviser career information available in 2026 and is intended for educational purposes only.

Looking for training support?

We offer CeMAP training for learners working towards a career in mortgage advice. Our courses follow the London Institute of Banking & Finance syllabus and are designed to support understanding of mortgage regulation and advice requirements.

Explore our accredited CeMAP training courses

> Futuretrend Financial Training