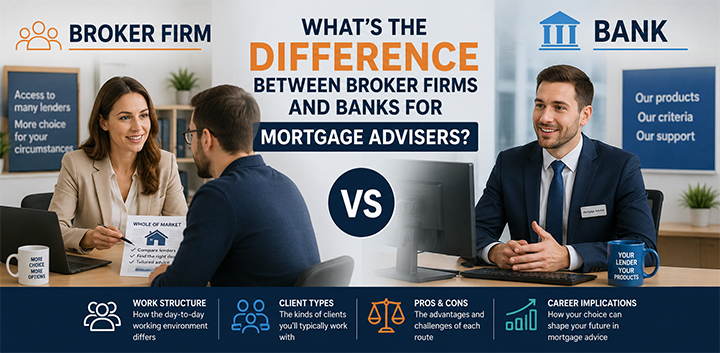
If you are starting a career as a mortgage adviser, one of the decisions you may eventually face is whether to work for a mortgage broker firm or a bank or building society. Both can provide a route into mortgage advice, but the day-to-day working environment can be quite different.
The main difference is the range of mortgage products you are able to advise on and the way clients reach you. A mortgage adviser working for a bank or building society will generally advise on products available from that particular lender. An adviser working for a broker firm may have access to products from a wider range of lenders, although the exact scope will depend on the firm and its proposition.
Neither route is automatically better. For a new mortgage adviser, the right environment depends on the type of work you enjoy, the support you need and where you would like your career to develop.
What Is the Difference Between a Mortgage Broker and a Bank Mortgage Adviser?
A bank mortgage adviser works for a particular lender and advises customers within that lender’s mortgage proposition. Their role is usually part of a larger organisation with established processes, systems, targets and management structures.
A mortgage broker works within an intermediary business. Rather than representing one lender’s mortgage range, the broker researches suitable mortgage products from the lenders available through the firm’s panel or sourcing arrangements.
This creates an important difference in the role.
A bank adviser may become very familiar with one lender’s criteria, products and internal processes. A broker needs to understand how different lenders approach areas such as affordability, property types, employment circumstances and lending criteria.
In both environments, however, mortgage advice remains a regulated activity. Advisers need the appropriate knowledge and competence and must work within the regulatory framework applying to mortgage advice.
How Does the Work Structure Differ Between a Broker Firm and a Bank?
Banks and larger building societies often have a more structured working environment. There may be clearly defined processes covering appointments, compliance, training, supervision and progression.
For somebody entering mortgage advice for the first time, that structure can be useful. You may have a manager, experienced advisers and dedicated compliance or training teams around you.
Broker firms vary much more.
A large national brokerage may have a structure that feels similar to a bank, with centralised systems, training and management. A small independent brokerage could consist of only a handful of advisers and administrators.
That does not necessarily mean a smaller broker provides less support. In some firms, new advisers work closely with experienced brokers and receive considerable one-to-one guidance.
The important point for new entrants is that “broker” does not describe one particular working environment. When considering a role, look at the individual firm rather than making assumptions based purely on whether it is a bank or brokerage.
Do Mortgage Brokers and Bank Advisers Deal With Different Clients?
They can, although there is considerable overlap.
A bank mortgage adviser may speak to existing customers of the bank as well as people who have approached that lender specifically for a mortgage. Clients may arrive through branches, telephone enquiries, online applications or referrals within the organisation.
This means the adviser may spend less time generating their own leads because the organisation already has an established customer base.
A broker firm may receive clients through online enquiries, estate agents, existing customer referrals, professional connections or marketing activity. Depending on the business model, individual advisers may also be expected to develop relationships and generate new business.
Brokers can also encounter clients whose circumstances require them to consider different lenders.
For example, a straightforward employed applicant with a good deposit may potentially meet the criteria of numerous lenders. Someone who is self-employed, has unusual income arrangements or is buying a less conventional property may require more research.
That can make brokerage work varied, but it can also increase the amount of research involved.
Does a Mortgage Broker Have Access to More Lenders?
Generally, a broker firm can consider a broader range of lenders than an adviser employed by a single bank, but you should not assume that every broker has access to every mortgage available.
Broker firms can operate with different lender panels and product arrangements. Some may offer advice across a broad part of the market, while others may work with a more restricted panel.
A bank or building society adviser is different because their advice is centred on that organisation’s own mortgage proposition.
For somebody considering a career in mortgage advice, this affects the knowledge required.
Within a bank, you may develop detailed knowledge of that lender’s criteria and processes. Within a brokerage, you may need to become comfortable comparing different lenders and recognising where criteria vary.
What Are the Advantages of Working for a Bank as a Mortgage Adviser?
One potential advantage is structure.
Larger financial organisations commonly have established training programmes, management structures, technology, compliance processes and defined responsibilities. This can provide a relatively clear environment in which to learn.
Other possible advantages include:
- an existing flow of customers and enquiries
- clearly defined procedures and processes
- access to internal training and support
- established compliance and supervision structures
- potential opportunities to move into other roles within a larger organisation
There can be disadvantages as well.
Your product range will generally be limited to the lender you work for, and larger organisations can have more rigid procedures. Targets and performance measures may also form a significant part of the working environment.
Someone who enjoys clearly defined processes may find that structure helpful. Someone looking for greater independence or a broader range of mortgage cases may eventually prefer another environment.
What Are the Advantages of Working for a Mortgage Broker Firm?
Brokerage can provide exposure to a wider range of lenders, criteria and client circumstances.
That variety can help an adviser build broad mortgage knowledge over time. Instead of asking whether a customer fits one lender’s criteria, the research process may involve identifying which available lender is appropriate for that customer’s circumstances.
Depending on the firm, potential advantages can include:
- exposure to multiple lenders
- varied client circumstances
- broader experience of mortgage criteria
- opportunities to develop client relationships
- potential routes towards more independent or self-employed work later in your career
There are also possible disadvantages.
The amount of support varies considerably between firms. Some roles may involve greater responsibility for generating business, managing a pipeline or maintaining professional referral relationships.
Smaller businesses may also have fewer formal career levels than a major bank.
For a new entrant, the name of the role therefore tells you less than the actual support structure behind it.
Is It Easier to Start Your Mortgage Adviser Career in a Bank or Broker Firm?
There is no single best starting point.
A bank may suit someone who wants a highly structured introduction to financial services. A broker firm may suit someone who wants early exposure to different lenders and a wider variety of mortgage cases.
However, the quality of the individual employer is more important than choosing “bank” or “broker” in isolation.
When comparing entry-level mortgage adviser jobs, look at how the employer supports somebody who is newly qualified or still developing competence.
Useful questions include whether you will have a dedicated supervisor, how cases are checked, what training is provided, how leads are generated and what is expected of you during your first few months.
A supportive broker firm may be a much better starting environment than a poorly supported role at a larger organisation, and the reverse can also be true.
How Could Your Choice Affect Your Mortgage Adviser Career?
Your first employer does not determine your entire career.
Mortgage advisers can move between banks, building societies, broker firms and other intermediary businesses as their experience develops.
Someone who begins with a bank may build strong experience in client conversations, regulated processes and mortgage applications before moving into brokerage.
Someone starting with a broker may develop broader knowledge of lender criteria and later decide to specialise, move to a larger firm or eventually explore self-employment.
There are also career routes beyond directly advising clients, including compliance, training, management, specialist mortgage advice and business development.
This is why your first mortgage adviser role should be viewed as a place to build practical competence, rather than a permanent choice between two sides of the industry.
Broker vs Bank Mortgage Adviser: Which Is Better?
Neither a broker firm nor a bank is inherently the better place to work as a mortgage adviser.
Banks and building societies can offer a more structured environment with established processes and an existing customer base, while broker firms can provide greater exposure to different lenders, mortgage criteria and client circumstances.
For someone entering the profession, factors such as training, supervision, workplace culture, lead generation and opportunities to gain experience are often more useful considerations than the type of organisation alone.
CeMAP provides the underpinning knowledge needed for a mortgage advice career, but becoming an effective adviser also requires practical development. Your first role is where much of that transition from learning mortgage advice to applying it with real clients begins.
Choosing between a broker and a bank is therefore less about finding the universally “best” option and more about finding the environment in which you can develop the skills, experience and confidence needed for the direction you want your mortgage career to take.
Looking for training support?
We offer CeMAP training for learners working towards a career in mortgage advice. Our courses follow the London Institute of Banking & Finance syllabus and are designed to support understanding of mortgage regulation and advice requirements.
Explore our accredited CeMAP training courses
> Futuretrend Financial Training