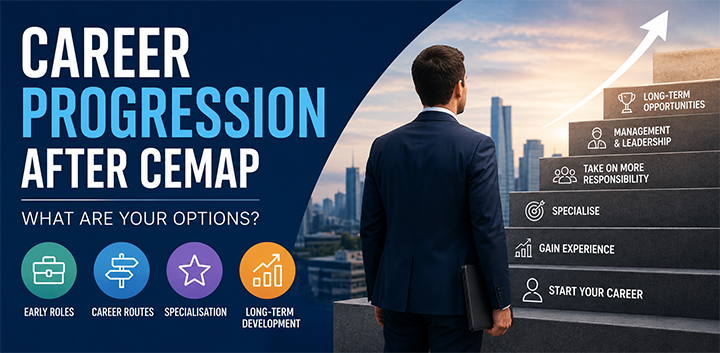
Passing CeMAP can open the door to a career in mortgage advice, but becoming qualified is usually the beginning of your professional development rather than the final destination.
For many new advisers, the first stage after CeMAP is about gaining practical experience, developing competence and learning how mortgage advice works with real clients. From there, there are several possible career progression routes, including becoming an experienced mortgage adviser, specialising in particular areas of the market, moving into management or training, or eventually becoming self-employed.
There is no single career path that every CeMAP-qualified adviser follows. Progression depends on your experience, performance, interests, employer and the type of mortgage advice you want to provide.
What Happens After You Pass CeMAP?
After passing CeMAP, the next step is normally to look for a role where you can begin applying your knowledge within a regulated mortgage advice environment.
CeMAP provides the knowledge and qualification needed for mortgage advice, but passing the exams does not mean that you immediately know how to handle every part of the job.
New advisers still need to develop practical skills such as conducting client conversations, gathering information accurately, researching suitable products, maintaining records and understanding their employer’s processes.
This is why the early stage of a mortgage career is often focused on developing competence rather than immediately trying to move into more senior positions.
Your CeMAP studies give you the foundation. Your first few years in the industry are where you begin building professional experience on top of it.
What Are the Typical First Jobs After CeMAP?
A newly CeMAP-qualified person may enter the mortgage industry through several different types of role.
Depending on the employer and your previous experience, this could include working as a:
- trainee mortgage adviser
- mortgage adviser
- mortgage consultant
- mortgage broker
- mortgage administrator or case manager progressing towards advice
- bank or building society mortgage adviser
Job titles vary considerably between employers, so it is important to look at what the role actually involves rather than concentrating entirely on its title.
Someone already working within financial services may be able to move directly into an adviser position after gaining CeMAP. Someone completely new to the industry may benefit from starting in a trainee or supporting role where they can become familiar with mortgage applications, lender requirements and client processes.
Neither route should automatically be considered better. The important point is that your first role allows you to build relevant experience and develop your ability to work with clients correctly.
What Do You Learn in Your First Mortgage Adviser Role?
Your first mortgage role helps turn the knowledge learned through CeMAP into practical professional skills.
For example, studying mortgage affordability is different from discussing income, expenditure and financial commitments with an actual client. Learning about mortgage products is also different from researching the market and explaining suitable options clearly to someone making an important financial decision.
Early career development may therefore involve improving your ability to:
- communicate with different types of clients
- gather accurate information
- understand client needs and circumstances
- research mortgage options
- explain complex information clearly
- maintain accurate records
- manage cases and deadlines
- work within regulatory and company procedures
- communicate with lenders, solicitors, estate agents and other parties
This practical development is an important part of becoming an experienced mortgage adviser.
CeMAP gives you essential knowledge, but experience teaches you how that knowledge fits together during real mortgage cases.
How Can a Mortgage Adviser Progress After Gaining Experience?
Once you have developed experience and demonstrated competence, your career can progress in several directions.
One option is simply to become a more experienced mortgage adviser. Career progression does not always require moving into management or changing job titles.
An experienced adviser may handle a wider range of clients, deal with more complicated circumstances or take greater responsibility within a brokerage or financial services business.
Others may decide to move to a different type of employer. For example, an adviser could gain experience within a bank or building society before moving into an independent mortgage brokerage, or move between firms to gain exposure to different types of clients and mortgage cases.
The right progression route depends partly on what you enjoy about the job.
Someone who enjoys working directly with clients may want to remain in advice and develop deeper expertise. Someone who enjoys coaching other advisers may eventually be more interested in management, training or supervision.
Can You Specialise After CeMAP?
Yes. Specialisation can become an important part of career progression for experienced mortgage advisers.
The mortgage market covers many different types of clients and circumstances. As advisers gain experience, some choose to develop stronger knowledge within particular areas.
This could include areas such as:
- buy-to-let mortgages
- later life lending
- protection
- complex income cases
- self-employed applicants
- adverse credit cases
- specialist lending
Specialisation normally develops through a combination of experience, additional learning and, where required, further qualifications.
It should not be rushed. Building a strong understanding of mainstream mortgage advice first can provide a useful foundation before concentrating on more specialist areas.
Some areas also have additional qualification or competency requirements. For example, advisers interested in particular forms of later life lending should check the relevant qualification and regulatory requirements before providing advice.
Can You Progress Into Mortgage Management?
Management is another possible career route after gaining sufficient industry experience.
Experienced advisers may progress into positions involving responsibility for a team, branch or group of advisers.
These roles can be quite different from spending the majority of the day advising clients.
A mortgage manager may be involved with performance, staff development, processes, quality standards and helping advisers deal with difficult cases. Depending on the organisation, management responsibilities may also include recruitment, coaching and operational planning.
Someone who is very good at mortgage advice will not automatically enjoy management. It requires a different combination of skills, particularly communication, organisation, decision-making and working with other people.
For advisers who enjoy helping colleagues develop, however, it can provide a natural longer-term progression route.
Can Mortgage Advisers Move Into Training or Compliance?
Experienced mortgage professionals may also move into roles connected with training, supervision, quality assurance or compliance.
These roles can suit people who develop a strong understanding of both mortgage advice and the regulatory environment surrounding it.
For example, an experienced adviser might become involved in coaching new advisers, reviewing cases, supporting competency development or delivering mortgage-related training.
Other people may become increasingly interested in regulation and compliance and choose to develop their career further in that direction.
These routes usually require more than simply having CeMAP. Relevant experience, further professional development and potentially additional qualifications may be important depending on the position.
However, practical mortgage experience can provide valuable context for careers that involve supporting or overseeing advisers.
Can You Become a Self-Employed Mortgage Adviser After CeMAP?
Self-employment can be a longer-term option, but passing CeMAP alone does not mean someone can simply begin operating independently as a mortgage adviser.
Mortgage advice is a regulated activity in the UK. Advisers and businesses must operate within the appropriate regulatory arrangements.
Some experienced advisers become self-employed while working through an established mortgage network or other authorised business structure. Others may eventually establish their own brokerage and pursue the appropriate regulatory arrangements for that business.
There are also significant commercial responsibilities involved.
A self-employed adviser may need to think about lead generation, client retention, administration, business costs, compliance and maintaining a consistent flow of work alongside actually providing advice.
For this reason, many people choose to gain substantial employed or supervised experience before considering self-employment.
Does Career Progression Mean Earning More Money?
Career progression can lead to increased earning potential, but there is no reliable figure that applies to every CeMAP-qualified adviser.
Mortgage adviser earnings vary according to factors including experience, employer, location, employment structure, client volumes, performance and whether remuneration includes commission or bonuses.
A self-employed adviser may also have a very different income and cost structure from an employed adviser.
This makes claims about what someone will earn after CeMAP potentially misleading.
A more useful way to think about career progression is in terms of increasing your experience, competence, responsibility and professional options. Greater earning potential may accompany that development, but it should not be treated as guaranteed.
What Does Long-Term Career Development Look Like for a Mortgage Adviser?
Long-term development as a mortgage adviser involves continuing to build knowledge and professional competence after qualifying.
Mortgage products, lender criteria, regulation and working practices change over time. Advisers therefore need to keep their knowledge current rather than relying entirely on what they learned when studying for CeMAP.
Career development might involve additional qualifications, employer training, continuing professional development, specialist knowledge or learning from increasingly complex client cases.
Over time, a CeMAP-qualified adviser could potentially develop towards:
Experienced mortgage advice
Building a long-term career advising clients and developing deeper knowledge of the mortgage market.
Specialist mortgage advice
Developing expertise in particular types of lending or client circumstances.
Management and supervision
Taking responsibility for advisers, teams or business operations.
Training and development
Helping new and existing advisers improve their knowledge and competence.
Compliance and quality roles
Moving towards the regulatory, monitoring or quality side of financial services.
Self-employment or business ownership
Developing a mortgage advice business within the appropriate regulatory structure.
These are possible routes rather than automatic stages. Someone can build a successful long-term career without progressing through all of them.
Do You Need More Qualifications After CeMAP?
You do not necessarily need to collect qualifications simply for the sake of career progression.
What you need depends on where you want your career to go.
For someone concentrating on mainstream mortgage advice, experience and ongoing professional development may initially be more useful than immediately starting another qualification.
For others, further study may become relevant when they decide to move into a specialist area or a different part of financial services. For example, if you would like to offer Equity Release to clients, then you are required to complete the add on CeRER qualification to be able to do so.
The important distinction is that CeMAP should not be viewed as the end of learning.
A strong mortgage adviser continues developing their knowledge throughout their career, whether that happens through formal qualifications, professional development, workplace training or practical experience.
What Is a Realistic Career Path After CeMAP?
A realistic career path after CeMAP often starts with gaining practical mortgage industry experience, becoming competent in client advice and gradually taking on greater responsibility.
From there, the path becomes much more individual.
One adviser might spend many years providing mortgage advice because working directly with clients is the part of the career they enjoy most. Another might specialise in more complex cases. Someone else might progress towards management, compliance or training, while an experienced adviser may eventually decide to become self-employed.
CeMAP therefore provides a starting point rather than a fixed career destination.
If you are considering CeMAP because you want a long-term career in mortgage advice, it can help to think beyond simply passing the exams. The qualification gives you the technical foundation needed to enter the profession, while your experience, practical skills and continued development will influence where your career goes afterwards.
Looking for training support?
We offer CeMAP training for learners working towards a career in mortgage advice. Our courses follow the London Institute of Banking & Finance syllabus and are designed to support understanding of mortgage regulation and advice requirements.
Explore our accredited CeMAP training courses
> Futuretrend Financial Training